A roof can become a financial decision as quickly as it becomes a construction decision. The goal is not to push one payment method. It is to understand the work, compare the available funding paths and choose an obligation that fits your situation and approved project scope.
Separate the construction question from the funding question
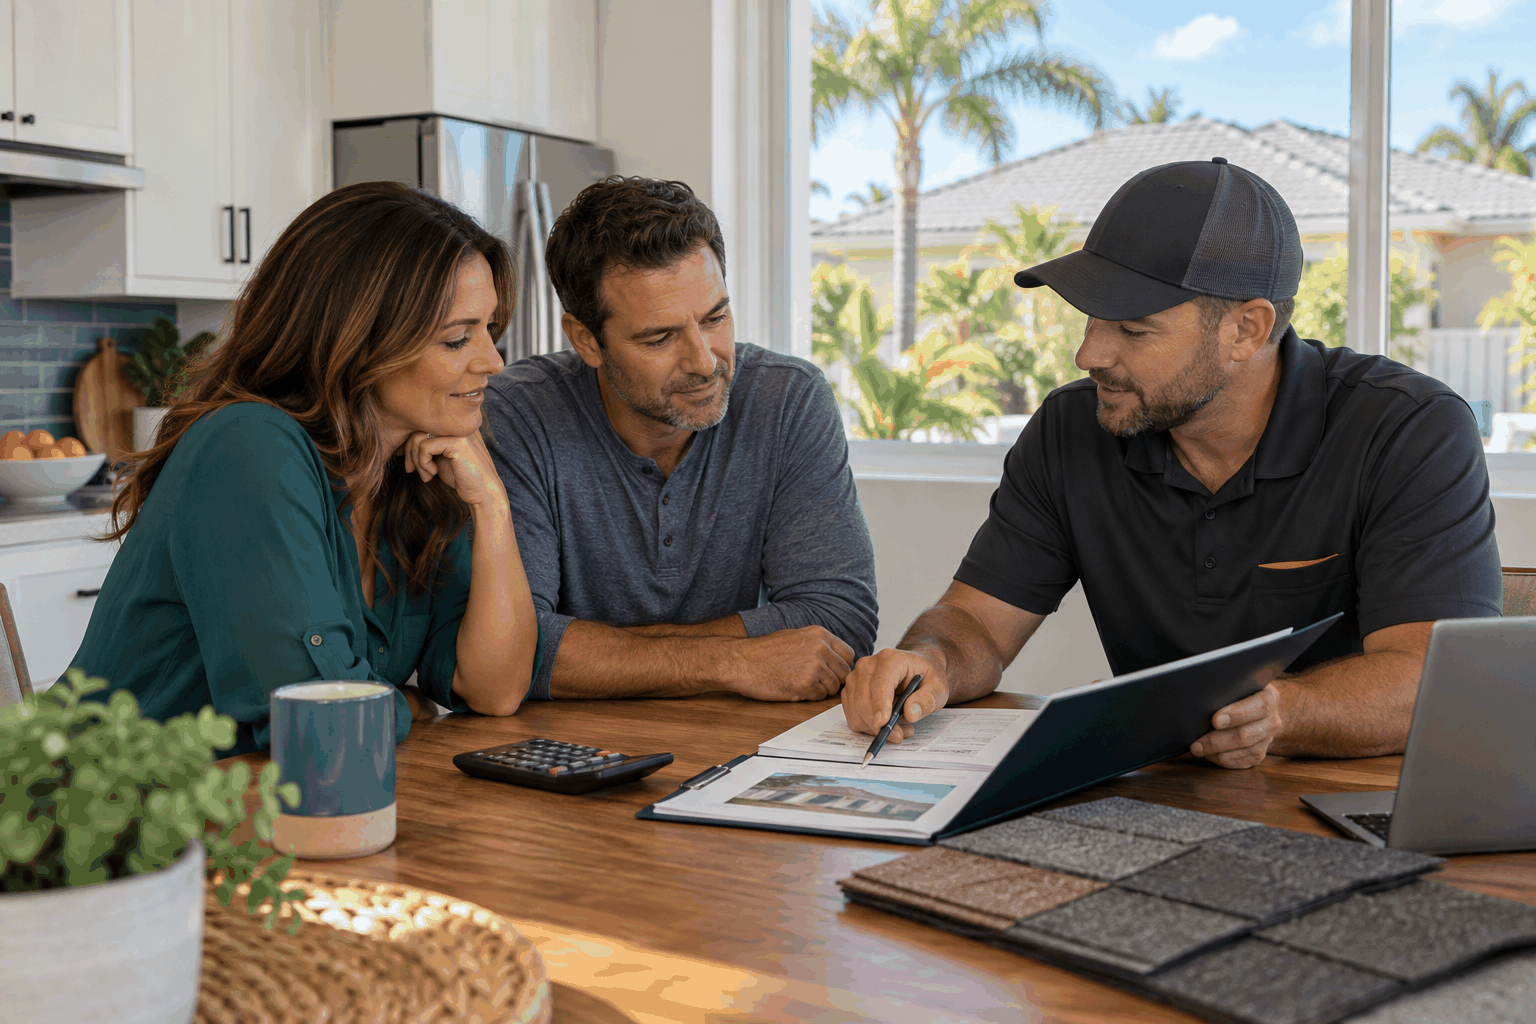
First understand what the property needs: emergency stabilization, targeted repair, replacement, remodeling or a broader project. Then ask for the scope, materials, schedule assumptions and payment milestones in writing. Financing cannot make an unclear scope clear, and a low monthly payment does not tell you the total cost of the project.
Once the scope is understood, you can compare cash, a card, a home-equity option, a personal loan or a funding-partner application when available. Terms, approval, rates and fees vary by applicant and provider.
Common paths homeowners consider
Cash can avoid interest but may reduce the funds available for emergencies and future maintenance. A credit card may be convenient but can become expensive if the balance is carried at a high rate. A home-equity line or loan may offer different terms but is secured by the home and requires careful review. A personal loan or contractor-connected funding partner may have its own approval process, term and fee structure.
These are not interchangeable. Compare the annual percentage rate, fixed or variable terms, fees, prepayment rules, total repayment, monthly payment and what happens if the project changes.
Start with a property-specific roof replacement scope so payment choices are tied to a real project.
Ask the questions that protect your budget
Before signing, ask who the lender or funding provider is, whether the contractor is paid directly, when the payment obligation begins and whether the project must be approved before funds are released. Ask what happens if weather delays the job or a concealed condition requires a change order.
Never assume approval, an advertised payment or a promotional rate applies to your situation. Review the actual offer documents and choose based on the complete obligation, not only the first number shown.
Funding through a partner
SOS can connect homeowners with available funding-partner information, including the Seven Figures Funding application path. A funding partner makes the approval decision and controls its own terms. Applying does not guarantee approval, a rate or a payment, and homeowners should review the provider’s disclosures directly.
The construction proposal remains a separate document. It should explain what SOS is doing, what is excluded, how change orders work and when payments are due.
Then compare the available options and provider limitations on the SOS financing page.
Plan for the full ownership picture
A roof is part of a property system. Budget for drainage, maintenance, future inspections and any work that must be completed to protect the new system. If a qualifying Coastal Shield maintenance plan is part of the proposal, read the written requirements carefully: the plan is a contractor-led care and documentation program, not insurance or a home warranty.
SOS Construction & Roofing can help you understand the construction scope, available payment conversations and the next steps for a free estimate. The funding decision remains yours.
- Compare total repayment, not only monthly payment.
- Read the actual terms and disclosures.
- Keep financing documents separate from the construction scope.
- Ask how change orders and delays affect payments.
- Do not assume approval or insurance coverage.
Need to understand the project before you apply? Start with a free estimate and a written scope, then compare the funding options available to you.
Start a free estimate request →